Renovating, Refinancing or Moving: Which Makes the Most Financial Sense?

Your home might be perfect in some ways, but not quite working for you anymore. Maybe your family needs more space, you’re tired of putting off that kitchen renovation, or you’re thinking about downsizing now that the kids have moved out.

If you’re a homeowner on Vancouver Island, you might be wondering whether it’s better to renovate the home you have, refinance your mortgage to access some of your home equity, or sell and move somewhere new.

There’s no one-size-fits-all answer. Each option comes with different costs, and the best choice depends on your finances, your current mortgage and what you want your home to look like in the years ahead.

Let’s break down what to consider before making a decision.

Option 1: Renovate the Home You Have

Sometimes, you don’t need a new house. You just need your current one to work a little better.

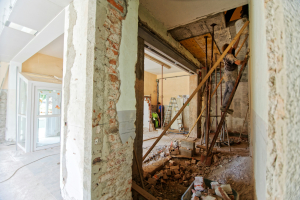
Maybe you want to update an older kitchen, add another bathroom, finish the basement or create more space for a growing family. Depending on the property, renovating could allow you to get more out of your home without going through the process of selling and buying again.

Before starting a renovation, think about:

  • Your budget: Look beyond the initial quote. Permits, professional fees, materials and unexpected expenses can add up, so it’s wise to leave room for surprises.
  • Your future plans: Will the changes meet your needs for the next five to ten years, or might you outgrow the space again?
  • The potential return: Some renovations may add value to your home, but you shouldn’t assume you’ll get back everything you spend.
  • How you’ll pay for it: Smaller projects might be covered by savings, while larger renovations could require financing.

If you’re happy with your neighbourhood and want to stay put, renovating may be worth exploring. But if the home needs major work or the layout simply can’t meet your needs, it may be worth comparing the cost with moving instead.
 

renovate or move vancouver

Option 2: Refinance Your Mortgage to Access Home Equity

If you’ve owned your home for a while, you may have built up equity through mortgage payments or changes in your property’s value.

Home equity is the difference between what your home is worth and what you still owe against it.

Depending on your financial situation and how much equity you have, you may be able to borrow against some of that equity to help fund renovations, repairs or other major expenses.

One option is refinancing your mortgage. This involves replacing your existing mortgage with a new one, potentially allowing you to borrow more than your current outstanding balance.

However, accessing your home equity isn’t free money. You’re taking on debt secured against your home, so it’s important to understand what the additional borrowing will cost.

Before refinancing, consider:

  • Your current mortgage rate: If you have a competitive rate, switching to a new mortgage could mean paying more interest.
  • Potential penalties: Breaking your existing mortgage before the end of its term may trigger a prepayment penalty.
  • Additional costs: Appraisal fees, legal fees and other expenses may apply.
  • Your new payments: Borrowing more could increase your monthly payments or the total interest you pay over time.

Refinancing isn’t the only way to access home equity. Depending on your circumstances, a home equity line of credit or another financing option may be worth discussing.

The important thing is to compare the available options and their total costs before deciding what’s right for you.
 

move or refinance vancouver

Option 3: Sell Your Home and Move

Sometimes, renovating isn’t the answer. Maybe you need more bedrooms, want a different layout, or are ready to downsize to something easier to maintain.

Selling and moving could give you the space or lifestyle you’re looking for, but it’s important to factor in the costs of both selling your current home and purchasing another one.

These costs may include:

  • Real estate commissions
  • Legal or notary fees
  • Moving expenses
  • Property transfer tax, where applicable
  • Costs associated with arranging a new mortgage

You’ll also need to consider how much money you’ll have left after selling your current home, paying off your existing mortgage and covering the costs of the sale.

If you’re moving to a more expensive property, you may need to take on a larger mortgage. If you’re downsizing, you could potentially reduce your mortgage balance and monthly expenses.

On Vancouver Island, where housing options and prices can vary between communities, it’s worth looking at what your current home could sell for and what you’d realistically need to spend on your next property.

The goal isn’t just to find a home that suits your needs. It’s to understand what the move would mean for your finances, both now and in the long run.

How Do You Know Which Option Makes the Most Sense?

Before committing to a renovation, refinancing your mortgage or putting your home on the market, take some time to compare the numbers.

Here are a few questions to ask yourself:

  • How much would the renovation realistically cost?
  • Would I need to borrow money to pay for it?
  • If I refinance, how would my mortgage payments change?
  • What could I expect to have left after selling my current home?
  • What would it cost to buy a property that better suits my needs?
  • How long do I plan to stay in my next home?

It’s easy to focus on one number, such as the cost of a renovation or the monthly payment on a new mortgage. But looking at the bigger picture can help you understand the financial impact of each option.

You may find that renovating is the most practical choice. Or you might discover that moving makes more sense than putting significant money into a home that no longer suits you.

And if you’re considering refinancing, reviewing your existing mortgage before making any decisions can help you understand what options may be available.
 

mortgage help vancouver island

Start With a Mortgage Review

You don’t have to make a decision on your own, and you don’t necessarily need to know which option you want before exploring your financing options.

At Mid Island Mortgage & Savings, we can help you review your current mortgage, discuss whether accessing home equity may be possible, and explore financing options for a renovation or a new property.

Every homeowner’s situation is different, so the first step is understanding where you stand and what you want to achieve.

Thinking about renovating, refinancing or moving? Get in touch with Mid Island Mortgage & Savings to talk through your plans and explore the mortgage options that may be available to you.

Mortgage financing is subject to lender approval, qualification requirements and property eligibility. Available options, costs and terms vary based on individual circumstances.
The Bank of Canada Held Rates — So Why Are Mortgage Rates Still Moving?

If you’ve been following mortgage rates lately, you may have noticed something that seems a little confusing.

The Bank of Canada held its overnight rate at 2.25% in September. So why are people still talking about mortgage rates moving?

If you’re buying a home in Nanaimo, renewing your mortgage on Vancouver Island, or simply trying to figure out what rates mean for your next move, it helps to understand that the Bank of Canada rate and your mortgage rate aren’t the same thing.

Different types of mortgages respond to different factors, which is why a Bank of Canada rate announcement doesn’t automatically tell you what every mortgage rate will do next.


First, what is the Bank of Canada overnight rate?

The Bank of Canada uses its policy interest rate to influence borrowing and spending across the economy.

When the Bank changes its overnight rate, that can influence other interest rates, including the prime rates set by financial institutions. Prime is then used as a reference point for many variable-rate loans and mortgages.

But the Bank of Canada does not set the mortgage rates offered by individual lenders.

That distinction is important.

So what happens to prime?

Prime rates are closely connected to the Bank of Canada’s overnight rate.

When the Bank changes its policy rate, lenders will generally adjust their prime rates as well. 

When the Bank holds its rate, there is no automatic prime-rate change resulting from that announcement.

For borrowers with a variable-rate mortgage tied to prime, this is one of the reasons Bank of Canada announcements matter.

But fixed-rate mortgages work differently.

Why don’t fixed mortgage rates simply follow the Bank of Canada?

This is where things get a little more interesting.

Fixed mortgage rates are influenced heavily by the cost for lenders to fund those mortgages. Government bond yields are one important part of that picture, particularly for longer-term fixed mortgages.

That means fixed mortgage rates can move even when the Bank of Canada hasn’t changed its overnight rate.

In fact, long-term bond yields can move based on things like economic conditions, inflation expectations, government borrowing and what investors expect to happen with interest rates in the future.

The Bank of Canada has recently highlighted that longer-term bond yields have remained elevated, even as policy interest rates have come down from their previous highs.

So you can have a situation where the Bank of Canada says, “We’re holding,” while the market that influences fixed mortgage pricing is still moving.


fixed rate vs. variable rate

What does this mean for variable mortgages?

Variable-rate mortgages are generally more directly connected to prime.

If your mortgage rate is based on prime, a change to your lender’s prime rate can affect your mortgage rate.

Exactly how that affects your payment depends on the type of variable mortgage you have. Some variable mortgages have payments that change as rates change, while others have fixed payments where the amount going toward interest versus principal can change.

That’s why it’s important to understand the specific terms of your mortgage rather than assuming every variable mortgage works the same way.

What does this mean for fixed mortgages?

Fixed-rate mortgages give you a set interest rate for your mortgage term, but the rate you are offered when you arrange or renew that mortgage is influenced by market conditions at that time.

So if you’re coming up for renewal in Nanaimo, for example, a Bank of Canada rate announcement is only one piece of the puzzle.

The overnight rate could stay exactly where it is while fixed mortgage pricing changes because bond yields or lender pricing have changed.

And the opposite can happen too.

What does this mean if you’re buying or renewing on Vancouver Island?

The biggest takeaway is that you don’t want to look at one number in isolation.

If you’re buying a home in Nanaimo, the rate you see today isn’t necessarily going to move in lockstep with the next Bank of Canada announcement.

If you’re renewing, a Bank of Canada hold doesn’t necessarily mean the rate available to you will be unchanged from what you were offered previously.

And if you’re trying to decide between fixed and variable, it helps to understand that those options are influenced by different factors.

So, should you be watching the Bank of Canada?

Absolutely, but don’t stop there.

The Bank of Canada rate can tell you something important about the broader interest-rate environment, but it doesn’t tell the whole story.

Fixed and variable mortgage rates respond to different factors, and lender pricing can change between Bank of Canada announcements

Whether you’re buying your first home in Nanaimo, moving somewhere else on Vancouver Island, or getting ready to renew your existing mortgage, understanding why rates move can help you make more sense of the numbers you’re being offered.

The next time you see a headline saying the Bank of Canada held rates, you’ll know there’s a little more to the story than that.

Looking at buying, renewing or refinancing? Talk to a mortgage professional at Mid Island Mortgage about how the current rate environment applies to your specific situation.

Reverse Mortgages: How to Access Your Home Equity in Retirement

For many homeowners, their home is their largest asset. After decades of mortgage payments, you may have built significant equity in your home, but that doesn’t necessarily mean you have extra cash available to enjoy life.

A reverse mortgage can be one way for homeowners aged 55 and older to access some of that equity while continuing to live in their home.

Whether you’re looking to supplement your retirement income, pay off an existing mortgage, make renovations or simply have more financial flexibility, it’s worth understanding how a reverse mortgage works and whether it could make sense for you.


What Is a Reverse Mortgage?

A reverse mortgage allows eligible homeowners aged 55+ to borrow against a portion of the equity in their home without having to sell or move.

You remain the owner of your home and can continue living there. Instead of making regular mortgage payments, the amount you borrow, along with accumulated interest, is generally repaid when you sell the home, move out or the last borrower passes away.

Depending on your circumstances, you may be able to access up to 55% of your home’s value. However, not everyone will qualify for the same amount.

How Much Can You Qualify For?

This is one of the most common questions we hear, and there’s no simple percentage that applies to everyone.

The amount you may qualify for depends on several factors, including:

  • Your age – Generally, the older you are, the more equity you may be able to access.
  • The value of your home – A higher-value property may allow you to access more equity.
  • The location of your home – The property location can affect lender eligibility and lending amounts.
  • The type of property – The property itself needs to meet the lender’s requirements.
  • Your existing mortgage or other debts registered against the property – These will need to be considered when determining how much equity is available.

This is why it’s worth having a conversation rather than trying to calculate your eligibility based on a percentage you see online.

What Can You Use a Reverse Mortgage For?

One of the benefits of a reverse mortgage is that the funds can be used for a variety of purposes. There isn’t one specific reason you need to have in order to consider one.

Some homeowners use the funds to:

Increase monthly cash flow:

If your retirement income isn’t stretching as far as you’d like, accessing some of your home equity could give you additional funds to work with.

Pay off an existing mortgage:

For someone approaching retirement with a mortgage still outstanding, a reverse mortgage may be an option to eliminate those regular mortgage payments.

Fund renovations:

Whether you’re updating your home, making accessibility improvements or simply tackling a long-overdue renovation, your home equity could help fund the project.

Cover care or other expenses:

Home care, medical care and other expenses can add up quickly. Accessing equity may provide another source of funds when needed.

Stay in your current home:

For many people, this is the biggest reason to consider a reverse mortgage. If you love your home and don’t want to downsize, accessing some of your equity could allow you to stay where you are.

Purchase another property:

In some situations, a reverse mortgage can also be used as part of purchasing a new property. This can be worth exploring if you’re considering a move but want to use your existing equity differently.


Do You Have to Sell Your Home?

No.

That’s one of the biggest differences between a reverse mortgage and simply selling your property to access your equity.

You continue to own and live in your home, provided you continue meeting the requirements of the mortgage and maintaining the property.

For someone who has lived in their home for decades, that can be a big deal.

Your home may be where your children grew up, where your neighbours have become friends and where you planned to spend your retirement. Downsizing isn’t necessarily the right answer just because you have equity in your home.

A reverse mortgage can provide another option to consider.

What About Downsizing Instead?

Downsizing may still be the better option for some homeowners.

Selling your current home and purchasing something smaller could free up equity without taking on additional borrowing. You may also reduce your maintenance costs and other expenses.

But it’s not the only option.

The right choice depends on what you want your retirement to look like, how much equity you have, your income, your expenses and whether staying in your current home is important to you.

That’s why the conversation should be about your options, rather than assuming there’s one right answer.


reverse mortgage vancouver

Is a Reverse Mortgage Right for You?

A reverse mortgage isn’t the right fit for every homeowner, and that’s okay.

For some, selling and downsizing makes the most sense. For others, refinancing or another home-equity option may be better. And for someone else, accessing their home equity may be exactly what allows them to stay in their home and enjoy retirement with less financial pressure.

The first step doesn’t have to be deciding.

It can simply be finding out what you qualify for and understanding what your options look like.

If you’re 55+ and wondering what your home equity could do for you, talk to Mid Island Mortgage & Savings. We can look at your situation, explain how a reverse mortgage works and help you determine whether it’s something worth considering.

Why More Buyers Are Choosing Clarity Before They Choose a Home

One of the most common things we hear is:

“I’m not sure if I’m ready to buy yet… but I’d like to know what’s possible.”

Those conversations are where the best plans start.

Because getting a mortgage pre-approval on Vancouver Island isn’t about putting pressure on yourself to buy a home tomorrow. It’s about understanding your options, building a plan, and knowing what steps will help you get there.

For many first-time buyers, the goal isn’t necessarily to buy today, it’s to have a plan for buying in the future. A mortgage pre-approval is one of the best ways to do exactly that.


mortgage pre approval vancouver island

A Pre-Approval Isn’t a Commitment

One of the biggest misconceptions about getting pre-approved is that it means you’re committing to buying a home.

It doesn’t.

A pre-approval is simply a conversation that helps you understand where you stand today. You don’t have to start house hunting next week, put in an offer next month, or even buy this year.

Instead, it gives you information you can use to make better decisions when the time is right.

It’s About Building a Plan

Many people assume a pre-approval is simply finding out the maximum amount they’ll qualify for.

In reality, it’s much more than that.

A planning conversation helps answer questions like:

  • What could I comfortably afford?
  • What would my monthly payments look like?
  • Am I ready to buy now, or should I wait?
  • If I’m self-employed, what income can I qualify with?
  • How much should I save before buying?
  • What documents will I need?
  • Is my credit where it needs to be?
  • How can I improve my buying power?

Those answers help you build a plan that’s based on your goals (not someone else’s timeline.)


first time home buyer

Sometimes the Best Advice Is “Not Yet”

This might surprise people, but sometimes the best advice we can give isn’t, “Let’s start looking at houses.”

Sometimes it’s:

  • Let’s pay down that credit card first.
  • Let’s wait until you’ve finished your probation period at work.
  • Let’s spend another six months growing your down payment.
  • If you’re self-employed, let’s wait until another year of income can strengthen your application.

Those conversations aren’t setbacks, they’re opportunities to put yourself in a stronger position before you buy.

If the Right Home Came Up Tomorrow…

Imagine you stumble across a home this weekend that’s exactly what you’ve been looking for.

Would you know:

  • If it’s within your budget?
  • What your monthly payments would be?
  • Whether you could confidently make an offer?

Or would you be scrambling to gather documents, estimate payments, and figure out if it’s even realistic?

A mortgage pre-approval gives you clarity before that moment arrives, so you can focus on the home not the financing.


first time home buyer Nanaimo

Small Changes Can Make a Big Difference

Another benefit of getting pre-approved early is that it gives you time to improve your buying power.

Sometimes a few small adjustments can make a meaningful difference, such as:

  • Paying down existing debt.
  • Correcting an error on your credit report.
  • Saving a little more for your down payment.
  • Structuring gifted down payment funds correctly.
  • Timing your purchase around changes to your income.

When you have time to plan, you also have time to improve your options.

Clarity Beats Perfect Timing

Mortgage rates will change. Markets will change. Life will change.

Trying to perfectly time your home purchase can leave you waiting for a moment that may never feel “perfect.” Instead, focus on the things you can control – understanding your budget, improving your buying power, and having a plan.

Whether you’re hoping to buy in a few months, next year, or you’re simply curious about what’s possible, having that conversation now means you’ll be ready when the timing feels right for you.

If you’re wondering where you stand today, we’d be happy to help you build a plan. Reach out anytime to get started.


The Two Money Conversations Every Family Should Have

At some point, many of us find ourselves having two very different conversations about money.

One is with the younger generation – helping them build good financial habits and prepare for milestones like buying their first home.

The other is with our parents – helping them decide whether their current home still fits their lifestyle and retirement plans.

These conversations can feel a little daunting, but they don’t have to be. We’ve broken them down into a few simple talking points to help you get the conversation started.


Money Talk #1: Helping the Next Generation

If buying a home is a goal, the best time to start planning is long before you’re browsing listings.

Build good credit

A good credit score doesn’t happen overnight. Paying bills on time, keeping credit card balances low, and borrowing responsibly can make a big difference when it’s time to apply for a mortgage.

Save with homeownership in mind

There are several great tools available for future homeowners, including:

  • FHSA (First Home Savings Account) – Tax-deductible contributions and tax-free withdrawals for your first home.
  • TFSA (Tax-Free Savings Account) – A flexible way to grow your savings.
  • RRSP Home Buyers’ Plan – Allows eligible first-time buyers to use RRSP savings toward a home purchase.

You don’t need to max these accounts out overnight. Even small, consistent contributions can add up over time.


Think before taking on new debt

A new vehicle or large line of credit might fit your budget today, but it can also affect how much you qualify to borrow later.

It’s one of the biggest surprises we see when people begin planning to buy their first home in Nanaimo. The more monthly debt payments you have, the less room there may be for a mortgage.

Talk to a mortgage broker early

You don’t need to wait until you’re ready to make an offer.

Having a conversation early can help you understand your options, set realistic goals, and make decisions today that support your future plans.

Understand the true cost of homeownership

A mortgage payment is only one part of owning a home.

It’s important to budget for things like:

  • Property taxes
  • Home insurance
  • Utilities
  • Maintenance and repairs

Having realistic expectations can help first-time buyers feel more confident when the time comes.

Money Talk #2: Helping the Previous Generation

Homeownership doesn’t stop once the mortgage is paid off.

For many homeowners, there comes a point where the question changes from “How do I buy a home?” to “Does this home still make sense for me?”

Is it time to downsize?

For some, the family home is now more space than they need. Downsizing can mean:

  • Less maintenance
  • Lower monthly expenses
  • A home that’s better suited to your current lifestyle


Helping parents downsize

Making the most of your home’s equity

After years of homeownership, your home may be one of your biggest financial assets.

Selling and downsizing could allow you to:

  • Eliminate mortgage payments
  • Free up money for retirement
  • Travel more
  • Help children or grandchildren with a down payment
  • Simply enjoy more financial flexibility

Every situation is different, but understanding your options is the first step.

Remember that it’s emotional, not just financial

For many homeowners, a house is more than just an asset. It’s where children were raised, holidays were celebrated, and memories were made.

If you’re having a conversation about downsizing, approach it with empathy. Rather than focusing only on finances, ask questions about what they want their next chapter to look like. The goal isn’t to convince them to move – it’s to help them explore what makes the most sense for their lifestyle and future.


first time home-buyer Nanaimo

It All Starts With a Conversation

Whether you’re helping your child prepare to become a first-time home buyer in Nanaimo or helping your parents explore their next chapter, planning ahead can make all the difference.

At Mid Island Mortgage, we’re here to help at every stage of the journey. Whether you’re buying your first home, reviewing your options, or planning for what’s next, we’re always happy to have a conversation.

Why Good People Still Get Declined for Mortgages — And What Can Be Done About It

One of the biggest misconceptions we hear is: “I probably won’t qualify for a mortgage.”

But the reality is, many situations aren’t as straightforward as they seem.

Mortgage approvals aren’t based on just one thing. Income, debt structure, credit history, property type, and even timing can all impact the outcome.

Let’s break down some of the most common reasons people run into issues with mortgage approvals (and how working with a broker can help.)

Your Credit History Matters More Than You Think

When lenders review a mortgage application, they want to see a history of responsible borrowing and repayment.

Missed payments, collections, unpaid taxes, or high balances on credit cards and lines of credit can all impact your approval chances and the type of mortgage products available to you.

That said, having bruised credit doesn’t automatically mean homeownership is out of reach.

How a Broker Helps

At Mid Island Mortgage & Savings, we have access to programs specifically designed for clients rebuilding their credit.

Different lenders have different levels of flexibility, and part of our job is helping clients understand what options may be available now and what steps could improve qualification in the future.

Sometimes a small plan and a little time can make a big difference.

Debt Payments Can Impact Your Buying Power

One of the biggest surprises for buyers is how much existing debt can affect mortgage qualification.

Lenders calculate what’s called a debt servicing ratio, which determines how much of your gross income can go toward:

  • housing costs
  • loan payments
  • credit cards
  • lines of credit
  • vehicle payments

For many traditional lenders, the maximum allowable ratio is 44% of gross income.

Even if you’ve already paid off most of a vehicle loan, the full monthly payment still counts in the calculations. Lines of credit and credit cards are also included based on the balance owing.

A large car payment or line of credit can sometimes reduce purchasing power more than expected.


mortgage approval vancouver

How a Broker Helps

A broker can help you understand how lenders view different types of debt and identify strategies that may improve qualification.

Sometimes restructuring debt, adjusting timelines, or exploring different lender options can make a meaningful difference.

Our goal is to help clients understand the full picture before they begin shopping for a home.

Self-Employment & Variable Income Can Be More Complex

Self-employed borrowers, contractors, commission-based workers, and individuals with fluctuating income often face additional challenges during the approval process.

Many lenders use a two-year average of reported net self-employed income to determine qualification. This means large write-offs or inconsistent income can impact borrowing power.

How a Broker Helps

At Mid Island Mortgage & Savings, we work with a variety of lenders that offer programs specifically for self-employed borrowers and non-traditional income situations.

Depending on the scenario, there may be stated income programs, extended ratio options, or alternative lending solutions available.

Every lender has different guidelines, which is why having access to multiple options can be valuable.


self employed mortgage approval

Property Type Matters More Than People Realize

Not every property is viewed the same by lenders.

Things like:

  • mobile homes
  • leasehold properties
  • rural homes
  • Gulf Island properties
  • strata properties
  • homes with pad fees

can all impact financing differently.

For example, strata fees are typically included at 50% in lender calculations, while mobile home pad fees are generally included at 100%. This can significantly affect qualification amounts.

A buyer may qualify for one type of property but not another – even at the same purchase price.


mobile home mortgage approval

How a Broker Helps

A broker can help identify potential property-related financing issues early in the process and match buyers with lenders that are better suited for certain property types.

This can help avoid surprises later on and create a smoother buying experience.

Why Pre-Approvals Can Change

Many buyers assume a pre-approval guarantees financing, but that’s not always the case.

A pre-approval is based on the information available at that specific point in time. If circumstances change, qualification can change too.

Things that can impact a pre-approval include:

  • taking on new debt
  • financing a vehicle
  • employment changes
  • co-signing for someone
  • changes to down payment
  • unpaid income taxes
  • rising interest rates after a rate hold expires

Most rate holds are valid for approximately 120 days and require an accepted offer and completion within that timeframe.

How a Broker Helps

One of the biggest benefits of working with a broker is having guidance throughout the entire process, not just at the beginning.

We help clients understand what actions could impact their approval and help navigate changes if circumstances shift during the home buying journey.

Sometimes avoiding one major purchase during the process can protect your approval entirely.

Why Working With a Broker Can Make a Difference

Every lender has different policies, strengths, and areas of flexibility.

Some lenders work better with:

  • self-employed borrowers
  • unique property types
  • bruised credit
  • higher debt ratios
  • alternative income situations

Banks can only offer their own products, while mortgage brokers have access to multiple lenders and programs.

At Mid Island Mortgage & Savings, our job is to look at the full picture and help find solutions tailored to each client’s situation.

The Bottom Line

Getting declined — or worrying you might get declined — doesn’t always mean homeownership is off the table.

Often, it simply means the strategy, timing, or lender needs adjusting.

The earlier you ask questions and explore your options, the more opportunities may be available.

If you’re unsure where you stand, we’re always happy to have a conversation and help you understand your options.

Understanding Fixed vs Variable Mortgage Rates in BC

When choosing a mortgage, one of the biggest decisions you’ll make is whether to go with a fixed rate or a variable rate.

It’s also one of the most misunderstood.

Many buyers automatically lean toward fixed rates for stability, but does that always make it the better option? Let’s break down the differences, look at historical trends, and help you understand what might work best for your situation.

What’s the Difference Between Fixed and Variable Rates?

Fixed Rate Mortgage

A fixed rate means:

  • Your interest rate stays the same for your entire term
  • Your payments are predictable
  • You’re protected from rate increases

This option is often chosen for peace of mind and stability.

Variable Rate Mortgage

A variable rate means:

  • Your rate can move up or down over time
  • It’s influenced by the Bank of Canada and lender prime rates
  • You may benefit if rates decrease

Some variable mortgages also have fixed payments, where only the portion going toward interest vs. principal changes.

Understanding the Risk (and Reward)

One of the best ways to understand risk is to look at what’s happened historically.

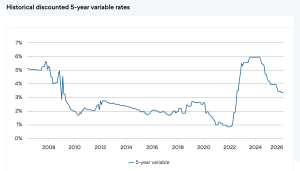
Looking at historical variable rates, we can see that while they do fluctuate, they’ve generally remained within a relatively moderate range.


variable mortgage Nanaimo

  •  Highest: ~5.94%
  • Lowest: ~0.90%

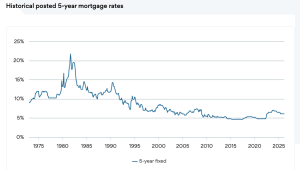
Now comparing that to fixed rates over time:

  • Highest: ~5.69% (in recent cycles)
  • Lowest: ~1.39

What This Actually Shows

While variable rates do move more frequently, the difference in extremes isn’t as dramatic as many people expect.

  • The highest variable rate was only about 0.25% higher than fixed
  • The lowest variable rate was actually lower than fixed by ~0.49%

In other words: Variable rates come with movement, but not necessarily extreme unpredictability AND can save you money in times where the interest rate has dropped.

Why Variable Rates Get a Bad Reputation

A lot of the hesitation around variable rates comes from recent rate increases. When rates rise quickly, it’s natural to want certainty (and fixed rates provide that.)

But historically:

  • Variable rates have often performed well over time
  • They’ve offered potential savings in many market cycles

That doesn’t make them “better,” just different.


mortgage expert Nanaimo

Pros of Fixed vs. Variable

Fixed Rate Pros

✔ Predictable payments 

✔ Protection from rate increases 

✔ Easier budgeting

Variable Rate Pros

✔ Potential for long-term interest savings

✔ Lower penalties if you break your mortgage early 

✔ Ability to benefit when rates decrease 

✔ Often more flexibility

So… Which One Is Better?

There’s no one-size-fits-all answer.

It comes down to:

  • Your comfort with change
  • Your financial goals
  • Your timeline
  • Your overall situation

Some people value stability above all else. Others are comfortable with some fluctuation in exchange for flexibility and potential savings.

Let’s Talk About What Works for You

If you’re unsure which option makes sense for your situation, that’s exactly what we’re here for.

We’ll walk you through the numbers, explain the trade-offs, and help you make a decision you feel confident about.

Reach out anytime to start the conversation.

First-Time Home Buyer GST Rebate in Canada

Buying your first home in Vancouver or on Vancouver Island can feel like a big financial step — especially with rising home prices and added costs like GST on new construction.

The good news? A new federal incentive is helping first-time buyers save significantly on newly built homes.

Here’s what you need to know about the First-Time Home Buyers’ GST/HST rebate and how it could apply to your purchase.

What Is the First-Time Home Buyer GST Rebate?

The federal government has introduced a new rebate designed to reduce — or eliminate — the GST on newly built homes for first-time buyers.

This means:

  • No GST on new homes up to $1 million 
  • Reduced GST on homes between $1 million and $1.5 million 
  • Potential savings of up to $50,000

This rebate can be used alongside the existing GST/HST new housing rebate, acting as an additional benefit.


first time home buyer gst rebate

Important Timing

One key detail is that this program is backdated.

The rebate generally applies to agreements of purchase and sale entered into:

On or after March 20, 2025 and before 2031

This means if you’ve already signed a contract for a new home after that date, you may still be eligible.

Who Is Eligible?

To qualify for the First-Time Home Buyer GST rebate, you must:

  • Be a first-time home buyer
  • Be purchasing a newly constructed home or substantially renovated 
  • Intend to use the home as your primary residence
  • Meet the program requirements set by the CRA

In many cases, eligibility will be reviewed alongside your mortgage application and closing process.


first time home buyer tax exemption Canada

What This Means for Buyers in Vancouver & Nanaimo

For buyers in markets like Vancouver and Nanaimo, where new construction prices are often higher, this rebate can make a meaningful difference.

It may: 

  • Reduce your upfront costs 
  • Improve affordability 
  • Help you qualify for a mortgage more comfortably

Even if you’re purchasing closer to the $1M–$1.5M range, partial savings can still be significant.

Why It’s Important to Plan Ahead

Programs like this can be incredibly helpful, but they also come with specific rules, timelines, and application processes.

Working with a mortgage professional early ensures:

• You understand what you qualify for

• You structure your purchase correctly

• You don’t miss out on available incentives

If you’re considering buying a newly built home in Vancouver or on Vancouver Island, it’s worth understanding how this rebate could apply to you.

Get in touch with us at Mid Island Mortgage and we can go over your options!

New to Canada and Ready to Buy? Mortgage Options in Vancouver & Vancouver Island

Canada continues to welcome newcomers from around the world—including many families relocating from the United States. If you’re new to Canada and planning to settle in Vancouver, Vancouver Island, or surrounding communities like Nanaimo, you may be surprised to learn there are mortgage programs specifically designed for newcomers.

As mortgage professionals serving Vancouver Island and beyond, we help new residents understand their options and navigate the additional steps that can come with buying property in British Columbia.

Here’s what you need to know about New to Canada mortgage programs.


Vancouver Island neighbourhood homes for newcomers buying property


What Is a New to Canada Mortgage Program?

Many lenders offer insured and uninsured mortgage options for individuals who have recently settled in Canada.

These programs are available to:

  • Permanent Residents who have relocated to Canada within the past 60 months
  • Temporary Residents / Foreign Workers with valid Canadian work authorization (work permit)

Each lender has slightly different guidelines, so reviewing your specific situation early is key.


Down Payment Requirements

New to Canada programs can fall under insured, insurable, or uninsured mortgage categories.

For insured mortgages, the minimum down payment is:

  • 5% on the first $500,000
  • 10% on the portion above $500,000

Your exact down payment requirement will depend on a full review of:

  • Income
  • Credit history
  • Employment status
  • Property type

Every application is assessed individually, which is why working with an experienced Nanaimo mortgage broker can make the process smoother.


People relocating to British Columbia with moving boxes and exploring mortgage options


What About Work Permits and Credit History?

For temporary residents, most lenders require:

  • A valid work permit
  • Typically at least 6 months remaining on that permit

Establishing Canadian credit strengthens your application. In many cases, lenders may also request:

  • An international credit report from your country of origin
  • Confirmation of employment income in Canada

Because of these additional layers, underwriting can take slightly longer than a standard mortgage approval.

Starting the conversation early gives you time to prepare documentation and avoid unnecessary delays.


Important: Property Must Be Your Principal Residence

New to Canada mortgage programs are generally available for owner-occupied homes only. Rental or investment properties are not eligible under these programs.

Additionally, eligibility related to Canada’s foreign buyer regulations, foreign buyer ban, and applicable taxes must be confirmed by a lawyer. It is important for buyers to understand all associated costs before proceeding with a purchase.


Why Work With a Mortgage Professional Early?

Buying a home in a new country can feel overwhelming. Mortgage guidelines, documentation requirements, and timelines may differ from what you’re used to.

Our role is to:

  • Review your full financial picture
  • Identify the most suitable lender program
  • Help you prepare required documentation
  • Guide you through the approval process step by step

If you’re new to Canada and considering buying a home in Nanaimo or the surrounding areas, speaking with a mortgage professional early in the process can make all the difference.


Thinking About Buying in BC or Alberta?

Whether you’ve just arrived or have been settling in for a few years, understanding your financing options is the first step toward homeownership.

If you’re exploring a New to Canada mortgage, reach out to our team at Mid Island Mortgage today. We’re here to help you navigate the process with clarity and confidence.

How Much Do You Need for a Down Payment in BC?

January is here — which usually means thinking ahead and dreaming a little bigger.

(We’re all doing it, right?)


And for a lot of people, becoming a homeowner is one of those goals that pops up every year around this time. It feels exciting… and then quickly overwhelming. Because once you start looking into it, there are a lot of moving parts:

  • How much money do I actually need?
  • What even counts as a down payment?
  • And how am I supposed to save while still surviving?

It’s usually at this point that the goal quietly gets pushed aside for “someday.”

So instead of trying to tackle everything at once, let’s start with the foundation — THE DOWN PAYMENT


How Much Down Payment Do You Really Need?

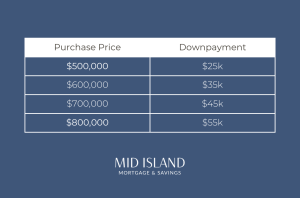
In Canada, the minimum required down payment depends on the purchase price of the home, and this applies whether you’re buying in British Columbia or elsewhere in the country:

  • 5% on the first $500,000
  • 10% on any amount above $500,000

Here’s what that looks like in real numbers for a down payment:

  • $500,000 home → $25,000 down payment
  • $600,000 home → $35,000 down payment
  • $700,000 home → $45,000 down payment
  • $800,000 home → $55,000 down payment

This is often where people feel discouraged because the total sounds big. But the key isn’t saving it all at once. It’s building toward your down payment consistently.


how much for a down payment bc

Turning a Big Goal Into a Realistic Savings Plan

One of the biggest mistakes first-time home buyers make is thinking they need to “figure it all out” before they start saving.


Instead, start with a monthly number.

For example:

Saving $700 per month for 3 years gives you approximately $25,200.

That alone could cover the minimum down payment on a $500,000 home in British Columbia.


For many people, that $700 already exists (it’s just going elsewhere.) A common example is a car payment. Driving an older vehicle a little longer and redirecting that monthly payment toward a down payment in BC can make a meaningful difference over time.

This is exactly where realistic goal setting matters. (If you read last month’s blog on setting grounded financial goals, this is a perfect example of how small, consistent decisions add up!)


saving for down payment

Smart Ways to Build Your Down Payment Faster

Saving in a regular account is a start — but there are better tools that can help you grow your down payment in British Columbia faster and more efficiently.

1. First Home Savings Account (FHSA)

The FHSA was created specifically to help first-time buyers in British Columbia.

  • Contributions are tax-deductible
  • Growth and withdrawals for a first home are tax-free
  • You can contribute up to $8,000 per year, with a lifetime maximum of $40,000

This means you lower your taxable income and grow your down payment at the same time.

2. RRSPs (Including the Home Buyers’ Plan)

Contributing to an RRSP can also help with your down payment.

  • Contributions reduce your taxable income
  • You may receive a larger tax refund
  • Through the Home Buyers’ Plan, you can withdraw up to $35,000 from your RRSP for a first home (and repay it over time)

A common strategy is contributing to an RRSP or FHSA, receiving a tax refund, and then putting that refund directly into savings toward your down payment.

With tax season coming up in February, now is a great time to start planning ahead.

3. TFSA Savings

TFSAs are another flexible option for saving for a down payment in BC:

  • Growth is tax-free
  • Funds can be withdrawn at any time

No tax impact when using the money for a down payment

Many buyers use a combination of TFSA, FHSA, and RRSP funds depending on their income and timeline.

4. Gifts From Immediate Family

Some first-time home buyers also receive gifted funds from immediate family members.

These are allowed, but they must be documented properly, and the lender will want to see where the funds came from. A mortgage professional can guide you through this process so there are no surprises.


first time home buyer british columbia


Start With a Conversation

You don’t need a perfect savings plan or a fully formed budget to get started.

What you do need is clarity:

  • How much down payment you’ll need
  • What tools make the most sense for you
  • How long your timeline realistically is

Even small steps, like opening the right account or setting up an automatic transfer, move you closer to buying your first home in British Columbia.


If buying your first home is one of your goals this year, starting the conversation early can make the process feel far more achievable and far less overwhelming.